Archy Raises US$50M to Replace Dentistry's Closet-Server Software
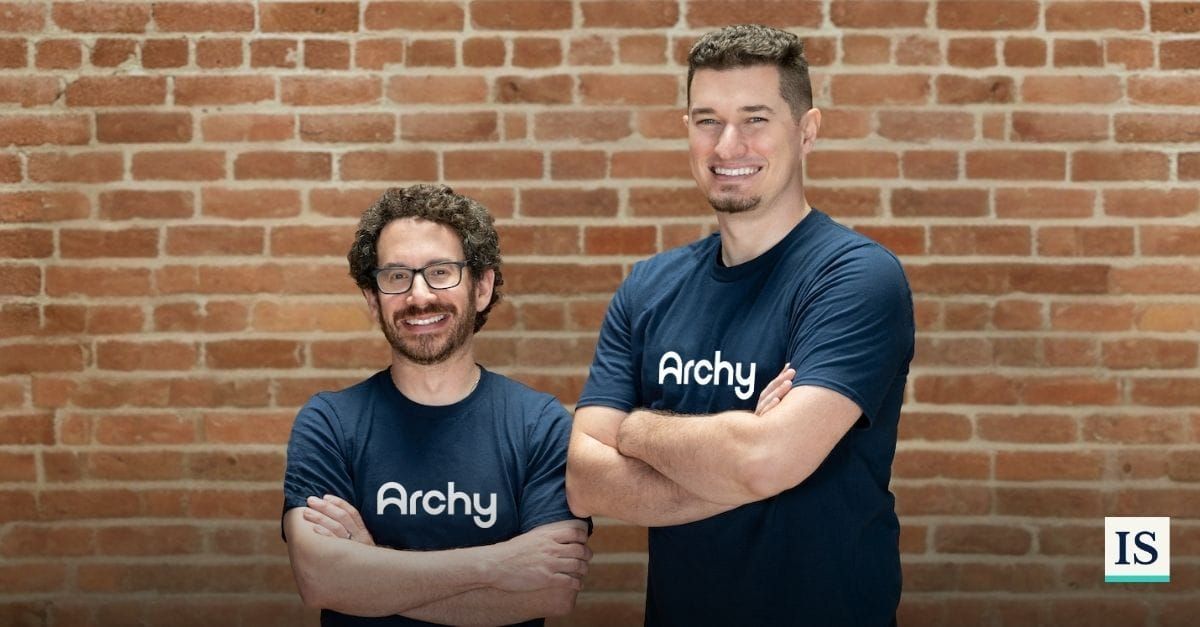
Archy, a San Jose, California company that sells cloud practice management software to dental offices, announced a US$50 million Series C on September 11, 2026. JMI Equity led the round, with existing backers TCV, Bessemer Venture Partners, CRV, Entrée Capital and Alven participating. The raise takes Archy's total funding to US$97 million since the company was founded in 2021 by chief executive Jonathan Rat and chief technology officer Benjamin Kolin, who previously rebuilt Uber's payments platform together and also worked at Meta and SurveyMonkey. The company will use the money to expand its lineup of AI agents for administrative work.
Archy runs scheduling, charting, imaging, billing, insurance and patient messaging in a single cloud system, then layers five AI agents on top: Archy Revenue for claims filing and collections, Archy Scribe for clinical notes, Archy Verify for insurance checks, Archy Connect for patient communications and Archy Insight for practice analytics. The platform now serves more than 1,000 dental practices across 45 states and processes over US$300 million in payments a year, up from US$100 million at the time of its US$20 million Series B in October 2025. The 130-person team includes operators from Toast, SurveyMonkey, Shopmonkey and Uber.
Market Context
The dental software market is still mostly running on the architecture Archy is selling against. Global dental practice management software was worth about US$1.96 billion in 2025 and is forecast to reach US$4.87 billion by 2034, a 10.77% compound annual growth rate, with North America accounting for roughly 54% of spending. The revealing number is deployment: on-premise systems still hold close to 68% of the market in 2026, meaning most practices are running their patient records on a physical server in the building. That installed base belongs to incumbents like Henry Schein One's Dentrix, Patterson's Eaglesoft and Open Dental, with Curve Dental as the established cloud alternative.
Investors have been funding dental AI aggressively, but mostly at the diagnostic layer. Pearl raised US$58 million in 2024 and Overjet closed a US$53 million Series C, both centered on reading radiographs. That segment was worth roughly US$421 million in 2024 and is projected to pass US$3 billion by 2034. Archy is going after a different budget, the back office, where the American Dental Association's Health Policy Institute puts insurance reimbursement and denials at the top of practice complaints heading into 2026, followed by hygienist shortages and overhead rising faster than reimbursement. Payment volume tripling in roughly ten months is the metric JMI appears to have underwritten, since it tracks both practice count and how deeply each practice runs on the platform.
What Stands Out
"Dentists are quickly realizing that slapping a shiny new AI tool onto 20-year-old software running on a server in the closet doesn't fix their core operational bottlenecks." — Jonathan Rat, co-founder and CEO, Archy
Regional Relevance
For the United States, this is vertical software catching up to the part of healthcare nobody underwrites. Dentistry sits largely outside the hospital IT budgets and federal incentive programs that pushed medical practices onto electronic records more than a decade ago, which is why so much of the sector still runs on-premise. A US$50 million round from a growth investor like JMI, which specializes in later-stage software rather than early bets, signals that the category has moved from a thesis to a market with proven unit economics.
The second signal is where the automation is aimed. Archy's agents target claims, verification and collections, the same revenue cycle friction that has driven medical billing automation, and they do it for independent practices rather than only for dental service organizations with in-house administrative staff. If the back office can be automated at the single-location level, the operating cost advantage that has fueled DSO consolidation narrows, which matters for the roughly 180,000 dentists in the country still deciding whether to sell to a group.
For Latin America, the read-through is timing rather than immediate opportunity. Dental care in the region is heavily private-pay and fragmented, which removes the insurance claims problem that anchors Archy's product in the US but leaves the scheduling, imaging and payments layer just as underserved. Regional health tech builders such as Brazil's Dental Office and Mexico's practice management vendors have the same incumbent problem and a cheaper cost of engineering, so the more likely path is local AI-native platforms copying the architecture rather than Archy expanding south. The constraint is payments infrastructure and data rules, not appetite.
The Other Side
Is the payment volume growth a product win or a pricing artifact? Payment processing revenue scales with volume, so tripling to US$300 million annually could reflect more practices, higher-billing practices, or simply more of each practice's transactions flowing through Archy instead of a third-party processor. The company did not break out software subscription revenue or ARR, and those are different multiples to an investor. Without that split, the headline metric is hard to compare against pure software peers.
Can a full-suite platform beat point solutions that practices already trust? Archy's argument is that AI only works when it sits on top of the whole workflow. The counterargument is switching cost: a practice that already uses Dentrix plus Overjet for imaging plus a separate messaging tool has to rip out its records system to buy Archy, and dental offices are famously reluctant to touch anything that touches the schedule. A thousand practices out of roughly 180,000 US dentists is real traction and also a very early market share.
What happens when the incumbents ship the same agents? Henry Schein One and Patterson own the installed base and the distribution, and both have been building cloud versions of their legacy products. They do not need to be better than Archy, only good enough to keep practices from migrating. Archy's window is the period before that catches up, which is also why the round is sized for speed rather than efficiency.
Sources & Transparency
- Archy Raises $50M Series C to Bring Dental Practices into the AI Era
- Archy Raises $50M Series C to Bring Dental Practices into the AI Era
- Archy Raises $50M Series C
- Archy Raises $50 Million To Build An AI-Powered Back Office For Dentists
- Exclusive: Founded By Uber Alumni, Archy Raises $20M To Put Dental Practices 'On Autopilot'
- Archy Raises $20M Series B to Put Dental Practices on Autopilot