
Ema Raises US$77M as Its AI Agents Push Enterprises Off Legacy SaaS
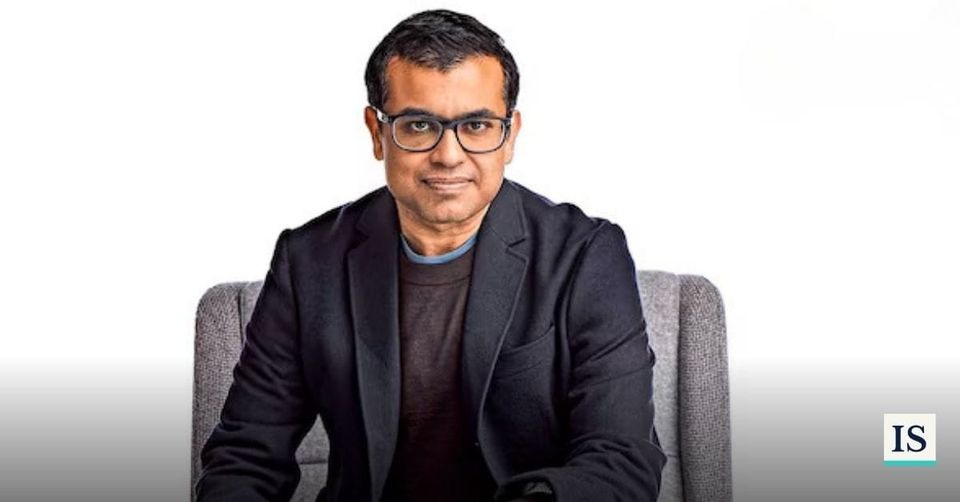
Ema, a San Francisco-based startup that deploys coordinated teams of AI agents to run HR, IT and finance processes inside large enterprises, raised a US$77 million Series B led by Creaegis, bringing its total funding to US$140 million. Existing investors Accel, Section 32 and Prosus all increased their stakes in the round, which was structured entirely as primary equity with no debt or secondary component. The company was founded in 2023 by Chief Executive Officer Surojit Chatterjee, a former vice president of product at Google and chief product officer at Coinbase through its IPO, and Souvik Sen, a former vice president of engineering at Okta who also led data and machine learning teams at Google. Ema emerged from stealth in March 2024 with a US$25 million round and raised its valuation to more than double its 2024 level in the new Series B, though the company has not disclosed a specific figure.
Ema orchestrates more than 150 underlying AI models to let a single "AI employee" complete multi-step workflows inside a company's existing applications, rather than automating one task at a time. The company says it now serves more than 50 active enterprise deals and over 1 million active users, with customers including Google, Microsoft, PwC, KPMG, NTT DATA, Hitachi, ADP and Wipro. Ema reports revenue bookings exceeding US$150 million on multiyear contracts, gross margins near 80%, and net dollar retention of roughly 180% as existing customers expand usage. Most of the new capital is earmarked for expanding sales and go-to-market operations, an area the company had underinvested in relative to product development, according to Chatterjee.
Market Context
Ema's raise lands as enterprise software buyers and their AI vendors are testing, in public, how far autonomous agents can go inside a company's existing tech stack. Gartner forecasts that 40% of enterprise applications will carry task-specific AI agents by the end of 2026, up from less than 5% a year earlier, and projects agentic AI could account for roughly 30% of enterprise application software revenue by 2035, up from about 2% today. That shift is drawing capital toward a crowded field of enterprise agent orchestrators, including Sierra, Glean, Moveworks and Decagon, all competing for the same enterprise budgets Ema is targeting, alongside incumbent SaaS vendors racing to embed agents of their own rather than cede the workflow layer.
The round is also notable for who is not new to the cap table. Rather than bringing in a fresh lead to validate a markup, Ema raised its Series B from the same investors who backed its Series A extension in 2024, Accel, Section 32 and Prosus, plus new lead Creaegis. Repeat conviction from existing backers, at a valuation more than double the prior round, is a different signal than a hot syndicate chasing a trend, and it comes as several richly funded AI agent startups have struggled to convert pilot deployments into the kind of retention numbers Ema is reporting.
The Claim
"Many of our customers are already on the way to replace [large SaaS applications] completely, removing dependency on them, because they are mostly becoming like a database." — Surojit Chatterjee, Chief Executive Officer and co-founder, Ema
Regional Relevance
For the United States, Ema's raise is a data point in a live argument about who captures the value created by enterprise AI: the incumbent software vendors that hold the systems of record, or the orchestration layer sitting on top of them. If large customers really do start treating platforms like Salesforce, Workday and ServiceNow as databases that AI agents act on rather than applications employees log into, the economics of enterprise software licensing, seat-based pricing above all, come under direct pressure. That reallocation of budget, from per-seat software fees toward outcome-based AI contracts, is one of the more consequential structural shifts working through corporate IT spending this year.
For the Bay Area venture ecosystem where Ema is based, the deal reinforces a pattern that has held through 2026: capital concentrating in founders with credible enterprise pedigrees rather than pure AI research backgrounds. Chatterjee's product record at Google and Coinbase, and Sen's infrastructure experience at Okta and Google, gave Ema access to enterprise buyers and repeat-investor conviction that newer entrants without that track record have struggled to match, a dynamic likely to keep shaping which agent startups clear later funding rounds as the category matures.
The Other Side
Is "replacing SaaS" a real product claim or a fundraising line? Ema's own numbers suggest usage expansion more than outright displacement: customers are growing spend by 180% in net dollar retention terms, which is consistent with adding more workflows to an existing software stack rather than ripping systems out. Enterprises rarely retire systems of record entirely, given compliance, integration and switching costs; the more likely near-term outcome is that AI agents shrink the number of paid seats on top of software that stays in place, not that the software disappears.
What happens when the model layer gets commoditized further? Chatterjee has argued that progress at frontier labs benefits Ema rather than threatens it, since better underlying models make its agents more capable without Ema having to build them. That logic holds only if Ema's differentiation is genuinely in orchestration, integration and workflow design rather than in the models themselves; if OpenAI, Microsoft or Google ship native multi-app agent orchestration as a platform feature, independent orchestrators face the same margin pressure that has hit thinner AI wrapper companies elsewhere.
Does the growth rate survive a tighter AI funding environment? A 50-fold revenue increase over two years and 180% net dollar retention are unusually strong figures, reported by the company rather than audited publicly. They are also the kind of metrics that get harder to sustain as the initial wave of enterprise AI budget experimentation matures into renewal decisions, where customers weigh actual productivity gains against contract cost rather than novelty.
Sources & Transparency
- Ema raises $77M as AI starts eating into enterprise software and services
- AI agent startup Ema completes $77 million Series B round led by Creaegis
- Ema, a 'Universal AI employee,' emerges from stealth with $25M
- Ema increases its Series A to $50M, with new funding led by Accel and Section 32
- Gartner Predicts 40% of Enterprise Apps Will Feature Task-Specific AI Agents by 2026, Up from Less Than 5% in 2025